
Home Loan vs Loan Against Property: Which One Should You Choose in Gujarat?

The purchase of a home and securing the loan are two distinct financial transactions. However, many borrowers tend to confuse between the two terms, Home Loan and Loan Against Property (LAP).
The distinction is simple: When someone takes a home loan, they are obtaining a loan to buy or build a house; when they take a Loan Against Property, they are getting a loan and using a property as collateral for that loan.
This is the reason it is important for the borrowers to understand this difference, particularly if they are considering buying a property or taking a loan in Ahmedabad, Gujarat.
So, which of the two should you take ? The answer is conditional upon your purpose, property ownership, repayment ability, loan amount, time of the loan, total cost of the loan and risk taking ability.
What Is a Home Loan?
Home Loans are loans that are secured and they are primarily used to help individuals buy or build their homes. Financing can also be obtained for other types of housing-related expenditures, depending on the product and lender.
If a person is looking to buy an apartment in Ahmedabad, he/she might need to avail a home loan to part-fin the same.
Typically, the property involved as the collateral is the property that is being financed. Income, credit history, and property information along with the lender’s policies can impact eligibility and loan terms.
Common Reasons for Taking a Home Loan
There are several reasons that make a borrower think about taking a home loan:
- Purchase of a new home
- Buying a resale home
- Constructing a house
- There are some requirements for renovating or improving that can be qualified.
- Other uses of housing allowed by the lender
One of the strengths is the particular focus on housing finance and not on general-purpose borrowing.
What is Loan Against Property?
A Loan Against Property (LAP) is a secured loan where the eligible property being owned by the borrower is put up as security.
The main purpose is not to buy the property being used to secure the loan; as with the home loan, the property is not primarily used for this purpose. Instead, the borrower uses the value of an existing residential or commercial property to raise funds for an eligible financial requirement.
LAP can be used as a factor in determining eligibility for loans including:
- Business expansion
- Working capital
- Education
- Medical expenses
- Other personal financial needs
- Debt consolidation (if allowed)
The allowed end use is subject to each lender and product, so borrowers should check the requirements prior to applying.
Home Loan vs Loan Against Property: Key Differences
| Factor | Home Loan | Loan Against Property |
| Main purpose | Purchase or construction of residential property | Raise funds against an existing property |
| Property | Usually the property being purchased/constructed serves as security | An already-owned eligible property is pledged |
| Fund usage | Primarily housing-related | Generally broader eligible purposes |
| Loan terms | Depend on lender and borrower profile | Depend on lender, property and borrower profile |
| Loan amount | Depends on property value and eligibility | Depends partly on property value and eligibility |
| Repayment | Monthly EMIs as per loan agreement | Monthly repayments as per LAP agreement |
| Collateral risk | The financed property is at risk in case of serious default | The pledged existing property is at risk in case of serious default |
| Tax treatment | Certain tax benefits may apply subject to prevailing tax law and eligibility | Tax treatment depends significantly on the purpose for which funds are used |
| Best suited for | Home purchase/construction | Eligible funding needs against owned property |
The comparison shows why Home Loan vs LAP is not really a question of which product is universally better. They are designed for different situations.
Which Is Better: Home Loan or Loan Against Property
There is not a right or wrong answer for each borrower.
A Home Loan May Suit You If:
- You’re buying a home or rental.
- You are constructing a residential property.
- The primary need is housing finance.
- You don’t have a different financial need that you’re looking to back up a property that you already own.
- You are looking for a mortgage loan that is designed for a home purchase or construction.
For instance, if an individual earning a salary is interested in buying a house in Ahmedabad, Gujarat, they are likely to research home loan options instead of seeking LAP for the house purchase.
A Loan Against Property May Suit You If:
The following situations may warrant considering LAP:
- You currently have an eligible property.
- Must have funds for a proper non-housing need.
- You wish to make use of the worth of a current home.
- You can afford to repay the loan.
- You have an understanding of the implications of pledging the property.
For example, a business owner with a business premise in Ahmedabad who owns a business property eligible for LAP might consider using LAP for a permissible business use.
But, taking out a valuable real estate as collateral is not an irretrievable borrowing move.
Home Loan vs Loan Against Property in Gujarat
The property market in Gujarat is diverse and there are loan takers who seek loans for buying properties and as well as for other property-backed loans.
In Ahmedabad, a home buyer could be thinking of purchasing an apartment, standalone house or any other home. Unlike an existing owner who is looking to borrow money to expand a business, their financing needs differ.
This separation is important for business owners and self-employed persons especially.
Suppose that two hypothetical situations exist:
Example 1 – Home Buyer:
A working professional is interested in buying a house in Ahmedabad. The main goal is to own a home, which means that a home loan could be the financing product under consideration.
Example 2 – Existing Property Owner:
An existing business possesses a property that is eligible for target area exemption but is looking for funds to expand their business. One alternative to consider is a Loan Against Property provided it meets lender criteria and the end-use requirements.
Neither of the examples above implies that approval is certain. The actual decision will be based on the financial profile of the borrower, property, documentation and lender policies.
Home Loan in Ahmedabad: What Should Borrowers Consider?
Borrowers should consider the advertised interest rate before they apply for Home Loan in Ahmedabad.
1. Calculate Your Affordable EMI
Avoid choosing a property solely based on a lender’s willingness to finance the property. Initially, think about the ease with which you can handle the EMI when you have your other household expenses and commitments.
2. Check Your Existing Obligations
Your ability to borrow may be influenced by your current EMIs, credit card balance and other financial obligations.
3. Evaluate the Property
It is important to verify property location, property title, whether the property has been approved, whether the property is constructed, and other documents before entering into a purchase.
4. Make comparisons for Total Cost
Look at the interest rate more than just the headline rate. Take into account any of the processing fees, documentation fees or other charges.
5. Understand the Tenure
A longer loan term can lower the initial EMI, but might lead to a higher interest paid overall. The correct time is contingent on your situation, and your lender’s.
Loan Against Property in Ahmedabad: What Should You Consider
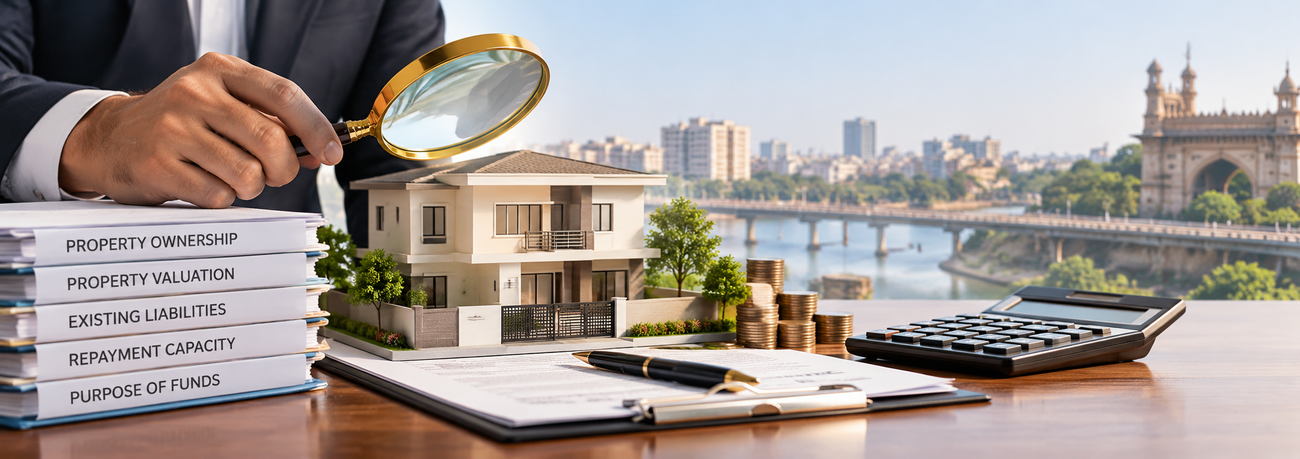
Loan against property in Ahmedabad also requires different assessment since you are having an existing property as the collateral.
Before applying, consider:
Property Ownership
Have clear ownership and title documentation, and have it accepted by the lender.
Property Valuation
The lender may take a look at the property before deciding on how much they are willing to provide.
Existing Liabilities
This may impact financing methods if the property is already mortgaged or encumbered in some other manner.
Repayment Capacity
Consider how much the proposed EMI would be if there is a decrease in income or reduced cash flow in your business.
Purpose of Funds
Make sure your intended use of the funds is permitted under the particular LAP product.
For instance a property owner in Bapunagar, Ahmedabad cannot take property ownership as an automatic right for LAP. The lender will evaluate the property, documents, borrower profile and other relevant factors.
Factors That Can Affect Loan Eligibility
The lenders take into account several factors when providing a Home Loan Gujarat or Loan Against Property.
These can include:
Income
When determining the repayment capacity, stable and documented income may be important.
Credit History
Your credit history shares information with the lender that lets them know how you have borrowed and repaid in the past.
Existing EMIs
The quantity of additional borrowing that you can comfortably support may be impacted by high existing obligations.
Age and Tenure
The repayment term and eligibility may vary depending on age.
Property Details
In the case of property-backed financing, the lender might look at ownership, location, legal status, valuation and other property-related considerations.
Employment or Business Profile
Documentation and assessment requirements may vary between loans for salaried and self-employed borrowers.
Every lender has its own set of requirements, so borrowers should contact the lender that they are interested in to find out what they need to meet at the time.
Documents You May Need
Borrowers generally may be required to provide the following:
For a Home Loan
- Identity proof
- Address proof
- Income documents
- Bank statements
- Documents relating to a job or business.
- Property-related documents
- Other lender specific documents
For a Loan Against Property
- Show identity and address proof.
- Income documents
- Bank statements
- Property ownership documents
- Details of existing loans (if applicable).
- The approval documents of the property and other documents related to it.
- Other lender-specific paperwork
It is best to thoroughly prepare documents instead of relying on a simple identity and income check.
Costs to Consider Beyond the Interest Rate
While interest rate is a key factor, it’s not the sole one.
There are some factors that borrowers should consider depending on the loan and lender, they are:
- Processing fees
- Evaluation charges (legal and technical) (where applicable),
- Documentation charges
- Stamp duty or registration fees for the property sale and purchase
- If applicable, the terms of prepayment or foreclosure would be included.
- Late-payment charges
- Other lender-specific charges
The treatment of the tax also varies based on the loan type and funds being used. The tax implication on home-loan benefits will be applicable as per the applicable tax policies and the tax implication for interest received on a Loan Against Property may vary depending on various aspects such as the end use of the borrowed amount.
Therefore, it’s crucial for borrowers to check the latest tax guidelines with a competent tax specialist.
Risks of Taking a Loan Against Property
LAP can offer you the money without selling a property, but it is also a serious risk – your property is serving as a collateral.
The pledge of the asset might be jeopardized if repayment is not made in accordance with the loan agreement and the account enters into the appropriate enforcement stage.
This is why it is significant to plan repayments.
Prior to enrolling in LAP:
- Is it possible to maintain the EMI comfortably?
- If my income goes down for a short period, what will happen?
- Do the borrowers really need the loan?
- Will my money provide me with enough financial benefit for what I’m using it for?
- Do I feel good sacrificing this property?
When deciding on a loan to purchase, it is important to factor in the realistic repayment plan, and not just what the lender will allow.
How to Decide Between Home Loan and LAP
There is a simple decision framework that can help.
Think About a home loan When:
You have a primary purpose of purchasing or building a home.
Think of a Loan Against Property When:
Own an eligible property, and require financing for a suitable financial purpose.
These are eight factors to consider before making a decision:
- Purpose of borrowing
- Existing property ownership
- Required loan amount
- Monthly repayment capacity
- Total borrowing cost
- Repayment tenure
- Collateral risk
- Lender-specific terms
This should not be to chase the lowest advertised numbers. You should be able to locate financing that fits your financial goal and would be able to pay for.
Common Mistakes Borrowers Should Avoid
1. Choosing Only by Interest Rate
A lower rate doesn’t necessarily mean a lower overall borrowing cost.
2. Borrowing More Than Necessary
Even if the amount is sanctioned, it does not imply that you must spend the entire sanctioned amount.
3. Ignoring Additional Charges
Other applicable costs, such as processing costs, should also be added when comparing loan offers.
4. Overlooking Existing EMIs
Make sure to consider your existing financial obligations before adding new debt.
5. Pledging Property Without Understanding the Risk
LAP involves collateral. Know what may occur if it will be hard to pay back.
6. Skipping Property Verification
Documentation of a property should be thoroughly analyzed prior to making a significant investment.
7. Assuming Approval Is Guaranteed
Approval of loans will be based on lender policies, eligibility, documentation, property assessment, etc.
8. Not Comparing Lenders
Different lenders can have different eligibility criteria, fees, processing requirements and terms.
Practical Checklist Before Applying
Before Taking a Home Loan
- Do the EMI calculations for a reasonable price
- assess your current financial commitments
- Review your credit report
- Decide on the amount of the down payment that you can afford.
- Verify property documents
- Compare lenders
- Recognize the total payment price of a repayment.
- Check the length of the lease and how much is due to be paid back.
Before Taking a Loan Against Property
- Establish title to the property
- Review current mortgages or liens.
- Appreciate the worth of property
- Calculate the correct quantity needed
- Compare lender terms
- Check eligibility requirements
- Assess repayment capacity
- Be aware of the repercussions of defaulting.
- Ensure that funds are used for approved end use
Final Thoughts
The primary difference between Home Loan vs Loan Against Property is that the question isn’t just “Which loan is cheaper?”
The better question is “Which loan fits my financial need and ability to repay?”
A home loan is usually used to finance a home and a Loan Against Property is a loan that can be taken against the property against other approved financial needs of the property owner. They can be helpful but come with various circumstances and dangers.
The key factors that need to be considered when making the right decision would be the purpose of the loan, property details, income, existing liabilities, total costs, and the long-term repayment capacity of borrowers in Gujarat and Ahmedabad.
EstateFin Global can be a local resource for property and loan related services while you’re looking for property and financing in Ahmedabad. EstateFin Global property services
FAQs
1. What is the difference between a Home Loan and a Loan Against Property ?
The main purpose of a Home Loan is to buy or build a house. With the Loan Against Property, the owner of an already owned eligible property can borrow money for the desired financial purpose.
2. Which is better, a Home Loan or Loan Against Property?
There is no one right or wrong answer. A home loan is typically the best choice for housing-related purposes, while LAP could be for an eligible homeowner seeking financing for another eligible purpose.
3. Can I use a Loan Against Property for business purposes?
LAP may be utilized for qualified business needs, like expansion or working capital, relying on the lender and product. Borrowers should confirm the end use of the loan before applying.
4. Can residential property be used for a Loan Against Property?
Lenders may accept eligible residential property based on the property’s eligibility for ownership, title, valuation and documentation and the lender’s policies.
5. What factors affect Home Loan eligibility in Gujarat ?
Eligibility can be impacted by income, credit history, current financial obligations, age, property information and lender-specific requirements. Some lenders may have different requirements.
6. What documents are required for a Loan Against Property?
These may include proof of identity and address, income documents, bank statements and property ownership documents. The exact list varies as per the profile of the lender and borrower.
7. What should I check before pledging my property for a loan?
Before signing onto, review the total cost of the loan, your ability to pay it back, the property’s valuation, the title documents, your current debts and obligations, and the lender’s terms of the loan and the effects of default.
8. Should I choose a Home Loan or LAP in Ahmedabad?
It depends on your purpose. If you are purchasing or constructing a home, investigate home-loan options. If you have an eligible home and require additional capital for a suitable non-housing purpose, you might want to consider LAP.